Payment Infrastructure: How It Works & Key Components
Payment infrastructure is the network of technology and compliance behind how payment infrastructure works, from authorisation to settlement. For payments product managers, understanding payment infrastructure is critical for managing operations and meeting regulatory obligations.
September 08, 2025
This article outlines the systems and participants that keep global transactions running and highlights the challenges and opportunities that come with building and maintaining reliable payment infrastructure.
What Is Payment Infrastructure?
Payment infrastructure means the network of systems, technology, and compliance that allows money to move securely from person to person, business to business, or banking institution to business and person. It not only supports money transfers across countries but also domestic transactions (think ACH) and various transaction types (credit card, bank-to-bank transfers, etc.).
In simple terms, payment infrastructure exists in card networks like Visa, Mastercard, American Express, Discover, and UnionPay. These card networks connect financial institutions and banks to merchants so customers can use debit and credit cards virtually anywhere in the world.
Most card payments run on what the industry calls the four-party model: the cardholder, the merchant, the issuing bank, and the acquiring bank, with the card network sitting between the two banks. Understanding this model matters because it explains where every fee, every rule, and every liability in the chain originates.
Closed-loop networks such as American Express and Discover collapse the issuing and acquiring roles into one company, which is why their pricing and acceptance terms behave differently from Visa and Mastercard.
Payments infrastructure is also not one single product. It is a stack:
Acceptance at the front: checkout, terminal, wallet
Routing and authorisation in the middle: gateway, processor, network
Money movement at the back: clearing, settlement, reconciliation
A team can buy the whole stack from one provider or assemble it from several using a modular payment infrastructure approach, and that choice determines how much of the operational burden stays in-house.
How Does Payment Infrastructure Work?
How payment infrastructure works comes down to moving funds from one party to another across several interconnected networks and systems in a secure fashion. There exists a regulated process by which steps and parties are organised to promote compliance, functionality, and speed.
The payment infrastructure process splits into three distinct stages that are often confused.
Authorisation: checks in real time whether the funds or credit exist and reserves them.
Clearing: exchanges the transaction records between the acquirer and the issuer through the card network so both sides agree on what is owed.
Settlement: the actual movement of money between the banks.
A transaction can be authorised and still fail to settle, which is why reconciliation exists as a separate discipline later in this article.
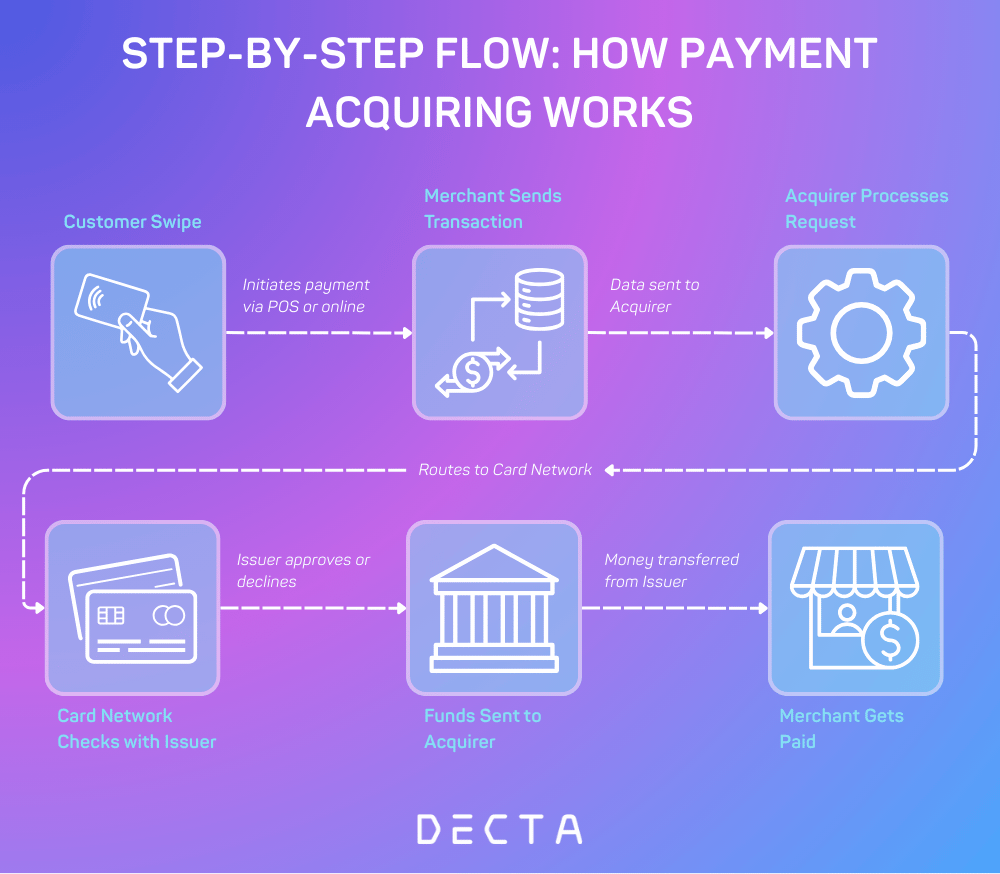
Step-By-Step Payment Flow
A transaction is created when a consumer chooses to pay with a credit card, debit card, digital wallet, or bank transfer. A point-of-sale system or checkout process logs the payment in question.
A payment gateway or payment processor secures sensitive data and transmits the appropriate transaction information to the designated payment processor for authorisation.
The payment processor communicates with the cardholder's issuing bank via various card networks or banking rails to determine if sufficient funds are available and whether the transaction is approved.
Should it be approved, the seller receives an authorisation code for the expected transaction value.
Next comes clearing, where the transaction is batched and submitted through the card network.
Then settlement: within one to three business days, the issuing bank wires the appropriate funds to the acquiring bank for acknowledgement by the seller.
Immediate authorisation is in place to prevent fraud and ensure that scammers can only attempt to steal a limited number of times, while settlement occurs to guarantee that the correct value is wired to the seller.
Payment Infrastructure Without the Build
DECTA operates end-to-end payment infrastructure across acquiring, issuing, and processing, certified for Mastercard, Visa, and UnionPay in the EEA and APAC.
There are numerous participants in the facilitation of every transaction:
Participant
Customer
Merchant
Payment Gateway
Payment Processor
Card Networks
Issuing Bank
Acquiring Bank
Regulatory Bodies
Role
Enters payment information
Enables the transaction via terminal or online interface
Facilitates secure transmission of payment data
Connects banks and entities to authorise or deny transactions
Independent entities (e.g., Visa, Mastercard) that set rules, route authorisation requests, and handle functions required for acknowledgement and submission.
Provides the customer’s card or bank account and approves/declines transactions
Provides the merchant’s bank account and receives funds for deposit
Monitor compliance efforts and enforce fiscal regulations
Key Components Of Payment Infrastructure
Payment infrastructure basics consist of a handful of interrelated components: technology, institutions, and security standards. Each component contributes to the flow of money from merchant to customer and vice versa, ensuring data and funds are appropriately secured along the way.
Payment Gateways
The payment gateway refers to the door to the digital payment vault for the merchant. It connects a merchant's website or card reader to the payment processor while gathering sensitive customer information and relaying it securely.
Payment gateways accept credit cards, digital wallets and sometimes direct bank transactions. They often provide merchants with ancillary benefits like fraud protection, tokenization solutions and e-commerce support.
Gateways also determine how much PCI DSS scope a merchant carries.
A hosted payment page or iframe keeps card data off the merchant's servers and reduces the compliance burden to the lightest self-assessment level.
A direct API integration gives full control over the checkout experience but pulls the merchant into far heavier audit obligations.
Without a payment gateway, a merchant can only take cash. Sensitive cardholder data can't be processed securely, and connections to card networks remain unfulfilled.
Payment Processors
Payment processors do all the work behind the scenes between the merchant, consumer bank and card network. Once engaged, the payment processor will authorise payment almost instantaneously, confirming that funds are in place and the total is accurate.
Beyond authorisation, the payment processor works by handling settlement, moving the collected funds from the transaction into the merchant's bank account.
Payment processors are good for chargeback alerts, resolution support, and recurring payments.
Processors also differ sharply in what they expose to the merchant. Transaction routing logic, retry rules, and support for multi-currency processing are what separate a basic processor from the kind of scaling payment infrastructure a growing business can stay on, because each of those directly changes the share of attempted payments that are approved.
If the processor consistently goes down, merchants lose out on revenue-producing transactions, and some merchants may find it impossible to scale in some areas.
Merchant Accounts
A merchant account is defined as a type of bank account that exists as an intermediary between debit and credit purchases and the merchant's actual business bank account. It holds the necessary funds until they can be moved into the owner-created account.
Various means are used to develop a merchant account; an acquiring bank creates a gateway entry to a merchant account and third-party payment services. Some merchants apply for their merchant accounts, and others aggregate with Square, PayPal, etc.
There are pros and cons to having a merchant account. Underwriting practices assess risk differently for a dedicated merchant account than for an aggregator, where thousands of businesses share one account.
A dedicated account takes longer to open and requires full underwriting, but it brings stable pricing and far lower risk of a sudden freeze.
An aggregator opens in minutes, which suits low-volume sellers, but accounts in higher-risk categories are terminated far more readily because the aggregator carries the exposure for everyone in the pool.
Issuing And Acquiring Banks
The issuing bank is where a consumer picks up their debit or credit card. This bank maintains active accounts associated with obtained credit cards.
The acquiring bank is what merchants use to accept payments via credit card. This bank connects merchants with other payment processors or external credit companies, but facilitates the transit of funds into the hands of the merchant.
The issuing and acquiring banks have to come to an agreement about how the funds are processed.
Payment Networks
Payment networks refers to Visa, Mastercard, American Express, Discover and UnionPay. They help facilitate payments from the issuing to the processing bank for credit card authorisation and settlement.
Payment networks determine how transactions clear and settle, and they set the interchange fee, which is the portion of every transaction paid by the acquirer to the issuing bank.
Interchange is usually the largest single line in a merchant's cost of acceptance, and because the network sets it rather than the processor, it is the one component no provider can discount.
Some payment networks exist on a wider scale than others; Mastercard and Visa are recognised worldwide. UnionPay is dominant in China and widely accepted across Asia, which makes it a required connection for anyone selling into those markets, while American Express and Discover operate closed-loop systems in which the network also issues and acquires.
Digital Wallets And Alternative Payment Methods
Digital wallets like Apple Pay, Google Pay and Venmo allow consumers to upload their cards into their phones, securely, and make contactless payments in person and online at physical retail outlets for expedited sales.
Regionally dedicated payment processors like WeChat or Alipay have become de facto comprehensive payment processors for all e-commerce needs in key markets. Each uses tokenization and device-specific measures to ensure purchases remain secure.
Alternative methods reduce reliance upon traditional purchase methods and expand avenues for accepting payments from international consumers who prefer nontraditional cards to credit.
For European merchants the practical list also includes bank-based methods:
iDEAL in the Netherlands
Bancontact in Belgium
Blik in Poland
Klarna for buy now, pay later
Each is a local default rather than a nice-to-have, and missing the dominant method in a market usually costs more conversion than any pricing difference.
Bank-Transfer And Instant-Payment Rails By Region
Payment rails are the underlying networks that carry money between bank accounts, and each region has its own set based on regulatory environments, technological prowess and market orientation. Differences in speed, features and pricing dictate how and when companies and consumers send money domestically and abroad.
Region/System(s)
EU/SEPA Credit Transfer
EU/SEPA Instant (SCT Inst)
US/ACH
US/RTP®
US/FedNow®
UK/Faster Payments Service
UK/Open Banking APIs
UK/VRP (Variable Recurring)
System(s)
1 business day
Seconds
1–2 business days
Real-time
Real-time
Seconds
Real-time
Variable
Notes/Adoption
Standard euro transfers
Limited bank adoption; €100k limit
High volume, payroll, billing
Larger banks; 24/7
New, broadening access to smaller banks
Default in many online banking apps
Enables account-to-account transfers
Consumer-controlled recurring payments
Each region also runs its own instant rail: SEPA Instant in the EU, Faster Payments in the UK, and RTP or FedNow in the US. Speeds and transaction limits differ between them, and adoption has moved fastest in the EU, where sending and receiving SCT Inst became mandatory for euro-area banks in October 2025 and the old €100,000 transaction cap was removed the same month under the EU Instant Payments Regulation. For the full region-by-region breakdown of how each rail works, see real-time payment infrastructure.
Types Of Payment Infrastructure For Different Businesses
The type of payment infrastructure needed varies by business according to the payment transaction environment, customer needs, and size of operation. Each model consists of different software and hardware solutions relative to security, efficiency, and reliability of processing payments.
E-Commerce Payment Infrastructure
E-Commerce retailers use a lot of payment gateways as they connect a page or application to a bank or card network relatively quickly. Payment gateways instantaneously authorise payments, and many involve encryption services that protect sensitive customer banking information.
Fraud prevention is imperative, as it creates a larger risk factor for consumers and their cards/unlicensed practices. Many merchants use 3D Secure authentication, machine learning fraud prevention, and address verification to combat chargebacks.
E-commerce businesses should also include as many payment options as possible. Credit/debit cards are often included, but sometimes digital wallets like PayPal, Amazon Pay, Apple Pay, and Google Pay are more commonly used. Global payment options can help expand conversion rates abroad.
In-Store Retail Payment Infrastructure
Brick-and-mortar retailers rely on point-of-sale (POS) terminals for processing card transactions using EMV chip technology, magnetic strips, and contactless capabilities. Manufacturers must all comply with PCI DSS rules to facilitate proper data protection.
Contactless readers are becoming increasingly popular as they expedite processing time. POS systems often integrate with loyalty or inventory control systems to facilitate a more seamless experience.
Omnichannel payment processing represents a new and growing infrastructural requirement of in-store retail locations, so customers can order something online and pay or send it to another location to pay. This requires physical and virtual infrastructure capabilities.
Marketplace And Platform Payment Infrastructure
Marketplace payment infrastructure allows multiple sellers to connect to buyers simultaneously; often, a multi-party settlement is required.
Payments need to be allocated between sellers, third-party providers, and the operating platform entity.
Marketplace platforms may require seller onboarding for multi-party operators to identify and account for additional services rendered by sellers. This includes KYC (Know Your Customer) guidelines as well as AML (Anti-Money Laundering) compliance. Automated onboarding allows faster seller participation under compliance controls.
Third-party marketplaces frequently use escrow services and delayed payouts, an inherent marketplace protection that ensures buyers are protected from fraud by ensuring that sellers receive payment only after fulfilling specific guidelines.
Fintech And Enterprise Payment Infrastructure
Fintech companies and large enterprises need a payment infrastructure that can facilitate high transaction volume while maintaining security and speed. This includes direct integration with banks, card providers, and alternative payments like cryptocurrency exchanges.
Larger entities require advanced reporting and analytics so they can monitor enterprise performance over time in multiple geographical locations and channels. Custom dashboards allow for regular data exports for effective reporting, compliance, reconciliation, and forecasting.
Integration flexibility is another priority, as larger companies must link their payment infrastructures with enterprise resource platforms (ERPs), customer relationship management (CRM) systems, and submission engines to make operations easier and reduce manual input.
A fintech running its own stack needs a few things beyond the basics: a ledger that can account for every movement of funds, versioned APIs and webhooks so integrations don't break as the platform evolves, and more than one processing or acquiring provider so a single outage or declined relationship doesn't stop transactions altogether.
Security, Authentication, And Compliance
Payment infrastructure technology is accompanied by the security of transactions, authentication and international compliance standards that safeguard financial information and prevent misuse. EMV chip transactions generate a unique cryptogram for every payment, so intercepted card data cannot be replayed, which is what effectively ended card cloning at the point of sale. The standards below cover what merchants and providers need in place; for the step-by-step practices to implement them, see security best practices.
PCI DSS
Payment Card Industry Data Security Standard (PCI DSS) refers to a compliance requirement mandated by regulation and applicable to any entity that creates or processes cardholder data.
PCI DSS compliance requirements include maintaining a secure network, protecting cardholder data and tracking/testing for vulnerabilities.
PCI compliance reduces the risks that cardholder data will be breached. In practice it means:
Only cardholder data which is encrypted, masked or tokenized is retained
Access to data is limited to personnel who require access for employment purposes
Comprehensive oversight with monitoring proceedings exists to thwart unauthorised actions
PCI non-compliance can lead to penalties, negative PR and termination of the ability to process credit card transactions.
Strong Customer Authentication
Strong Customer Authentication (SCA) is defined as a legal requirement set forth by the European Union's Payment Services Directive 2 (PSD2) legislation. The goal of SCA is to reduce fraud and increase customer trust by requiring a minimum of two independent factors to support customer authentication.
Factors supporting authenticating validation fall into three categories.
Something the customer knows (e.g., password or PIN)
Something the customer has (e.g., mobile device or card)
Something the customer is (e.g., fingerprint or facial recognition)
Standards like EMV 3-D Secure 2.x champion SCA by enabling biometrics authentication and one-time dynamic character strings.
Tokenisation And Encryption
Tokenisation and encryption are two ways to protect sensitive payment data, but they work differently.
Encryption: takes sensitive information and scrambles it into unintelligible code, which only returns to decipherable data form with the appropriate decryption key.
Tokenisation: takes sensitive information and gives it a randomised replacement, a token, which has no real value anywhere else but on its originating platform.
For example, encryption works well for sensitive data in transit, meaning that when someone is entering payment information online, their sensitive data is protected.
Tokenisation works best for sensitive information at rest because if a hacker were ever to get access to payment systems, they'd want to expose true credit card numbers.
It's very common for tokenisation and encryption to work hand in hand. If a hacker gets a hold of payment data or somehow accesses a transaction system, their efforts will be rendered useless if they've only encountered scrambled or tokenised information.
AML/CFT And KYC
Anti-Money Laundering (AML) and Counter-Terrorist Financing (CFT) requirements compel payment processors to monitor ongoing activity and report anything suspicious that could lead payments to support illegal activities.
Financial institutions must submit suspicious activity reports (SARs) or suspicious transaction reports (STRs) to financial regulatory authorities if they feel something is awry based on transaction trends.
Know Your Customer (KYC) refers to the first line of defence because it requires legitimate businesses to authenticate customer identity through sanctioned checks and risk profiles before they can access any services.
AML, CFT, and KYC compliance reduces the likelihood that a transaction gets processed for illegal reasons.
Risk, Fraud, And Disputes
Payment infrastructure has to protect against pending risks that can stop payments in their tracks, breach personal information and take money from all parties involved. The most effective systems minimize fraud risk and allow for any disputes to be processed in a transparent, measurable manner.
Fraud Risk Controls
Multiple risk controls are in place to help merchants minimise fraudulent activity or identify suspicious actions before they escalate into fraud.
Device fingerprinting assesses the characteristics of a user's device, which makes it harder for someone engaging in illicit activity to camouflage their actions.
Behavioural analytics assess how a user is interacting with the checkout page and flags activity that does not conform to expected behaviours, like account takeovers or bot-generated behaviour.
Ultimately, there's real-time transaction monitoring, inclusive of velocity checks that identify transactions that attempt to go through at lightning speed or rapidly sequenced attempts to pay, which are not typical behaviours.
There are also negative list monitoring and positive list tracking; merchants are aware of known fraudsters and frequently transacting customers/merchants, which aids decision-making.
Additionally, there is a fraud risk score generated by card networks, which provides a real-time determination as to whether to proceed with a payment, decline it or defer it for further review.
Method
Device Fingerprinting
Behavioural Analytics
Velocity Checks
Negative/Positive Lists
Fraud Risk Score
Chargebacks & Representment
Adaptive Authentication
How it Works
Profiles a user's device to detect anomalies
Monitors interaction patterns to flag unusual behaviour
Flags rapid or excessive transaction attempts
Tracks known fraudsters and trusted customers
Card networks generate real-time risk evaluation
Customers dispute transactions; merchants may fight back with evidence
Adds extra validation at checkout
Best For
Identifying suspicious devices or sessions
Detecting bots and account takeovers
Preventing automated fraud attempts
Faster decisions on risky vs. reliable users
Deciding to approve, decline, or review transactions
Handling disputes and reducing losses
Reducing fraud and limiting chargebacks
Chargebacks And Disputes
Disputes can still arise in the form of chargebacks; when a customer does not agree with a transaction, a chargeback takes place.
Each chargeback is assigned a reason code, which helps merchants determine whether it's transaction-based due to fraud, failure to receive goods, or improper processing. Merchants constantly monitor their chargeback ratios since excessive chargebacks incur penalties from payment processors.
Merchants can utilise representment to dispute chargebacks to fight them; merchants provide evidence that a charge was legitimate. The likelihood of success rates for representment is reliant upon the quality of documentation provided and the processor's rules.
Yet now, with adaptive authentication becoming more commonplace, more information is validated at the point of sale transaction than ever before, resulting in fewer chargebacks reaching this level.
Settlement, Funding, And Reconciliation
Settlement works by moving the funds from the customer bank account to the merchant bank account while funding occurs on an agreed-upon timeline or payment rails.
Thereafter, reconciliation and reporting ensure client accuracy, regulatory requirements and proper financial controls.
Settlement And Funding Timelines
The funding timeline varies based on the payment type and the payment network it's attempting to fund.
Card-based transactions generally settle from T+1 to T+3 business days. Merchants should see funding hit their accounts anywhere from one business day after the date of the transaction up to three business days after the date of the transaction.
This lag exists for clearing, fraud detection/recovery and access to acquirer-funding.
For example, with ACH-based transactions, the funding time window can be longer for returns. A consumer debit could be reversed for up to 60 days, and even for business debits, there could be a 2 to 5 day timeline for debits. Until these time windows close, merchants are exposed to at least partial reversal.
With instant payment rails, however, payment posts at the moment (real-time bank transfers) and when payment is confirmed, it usually is irrevocable.
Thus, while this provides security and faster access to cash flow, fraud/error detection must be extremely vigilant since there are no recourse options.
Transaction Type
Card-Based Transactions
ACH (Consumer Debits)
ACH (Business Debits)
Instant Payment Rails
Settlement Speed
T+1 to T+3 business days
Up to 60 days for reversals
2–5 business days
Real-time
Notes
Standard lag for clearing and fraud checks
Extended reversal risk exposure
Shorter reversal window but still risky
Irrevocable once confirmed; requires strong fraud detection
Reconciliation
Reconciliation is important here as processors or acquirers report one total, but the merchant receives a different total in checking. The finance team needs to match daily transactions to daily settlements to daily bank statements to ensure everything reconciles.
Part of this may include analysing fees, foreign exchange adjustments and batch settlements. For companies with multiple currencies across a few different payment rails, reconciliation is critical and complicated with reporting requirements.
Common reconciliation efforts include:
Reconciling transaction IDs received through settlements and batches
Reconciling fee deductions of credit card charges and chargebacks
Reconciling timing discrepancies for authorisation and settlement
Proper reconciliation eliminates lost revenue, enables better transparency of funds and audit compliance.
Controls And Reporting
Proper controls and reporting ensure errors can be reduced with compliance efforts from financials. For companies that are held to a certain standard by efforts like Sarbanes–Oxley (SOX), there should be supporting documentation required in the settlement and reconciliation process, tracked through proper reporting.
Controls include separation of duties, automated exception reporting roles and settlement file inclusive audits.
Being able to audit/document the process provides traceability as well as support for both internal and external investigations.
The reporting includes settlement turnaround times, reconciliation findings, open exceptions and the like.
Build Vs Buy: Architecture Choice For Payments Product Managers
There are two ways to build payment processing infrastructure: building it in-house or buying third-party service provider offerings. Compared to buying, building trades speed to market for control over architecture, while buying trades customisation for predictable cost and compliance coverage.
Building in-house gives full control, but it takes longer, requires holding your own licences, and means ongoing compliance work as scheme rules and standards evolve.
Buying is faster to market with known costs, but it makes you dependent on the vendor's roadmap, one reason it is worth planning against payment infrastructure lock-in from the start.
If a switch does become necessary later, changing provider is a project of its own: see payment infrastructure migration for how to minimise the risk and downtime involved.
The future of payment infrastructure trends toward faster settlement, interoperability, and intelligence. Government, financial services, and technology stakeholders each develop systems that promote speed, transparency, and better control over who sees and uses their data.
Instant, Always-On Rails
Real-time payment rails are becoming standard worldwide, settling transfers in seconds around the clock. For a full breakdown of how these rails work, see real-time payment infrastructure.
For example, India's Unified Payments Interface (UPI) and Brazil's Pix are instant settlement solutions that work for millions of transfers. They reduce merchant transaction costs and promote financial inclusion, as even the smallest micro businesses can access and provide digital payment solutions without ancillary fees.
Always-on rails enable cross-border breakthroughs, too. While many real-time rails are established domestically, central banks and regulators are conducting their studies into interoperability frameworks that connect real-time rails internationally.
This would alleviate sought-after concerns regarding remittance pricing because today's cross-border transfers can exceed 10% in transaction fees and take days to settle.
Open Banking / Pay-By-Bank
Open banking is about changing the fundamentals of how payments are authenticated and processed.
By allowing for secure access to bank accounts through APIs, a third-party provider can facilitate payment directly from a customer's bank account instead of relying on card-based networks. This is tied to "pay-by-bank."
Compared to card acceptance, merchants get lower transaction costs with pay-by-bank models and quicker settlements. Chargeback risk is minimal, as payments come directly from bank authorisation. There's no grey area with transparent access; a customer either authenticated a payment, or he/she did not.
For consumers, payment becomes more transparent, as it occurs through secured authentication devices, whether a biometric finger scan or a token provided by one's bank.
PSD2 in the European Union has driven open-banking initiatives since banks must offer licensed third-party provider access to foster new verticals to compete with traditional card-based payments.
AI In Payments
Artificial intelligence is taking payments beyond fraud prevention. Machine learning tools identify patterns of unusual activity in real time, reducing false declines while simultaneously increasing protection efforts.
For example, risk scoring and anomaly detection apply to high-volume payment processors, which can determine behaviours over time. AI can reveal whether a merchant frequently returns to a consumer's portal or whether an issuer declines most payment requests; by adjusting the expected approval prediction for future transactions based on the trend, declines are avoided and losses reduced.
There's also decline-code remediation and retry optimisation. Instead of simply declining a payment, AI can acknowledge decline trends, whether technical or issuer-related, and retry in a different capacity to approve the transaction. When applied at scale, it increases acceptance rates for merchants.
Regional Sovereignty Initiatives
Regions want local options that prevent reliance on international networks. Payment sovereignty is about local governments having control over transactional data, fees, and system resiliency.
UnionPay dominates China, as do domestic ecosystems like Alipay and WeChat Pay. Similarly, India's UPI and Brazil's Pix have been adopted nationally with billions of transactions monthly, bolstering the local ecosystem and reducing dependence on international card networks.
In Europe, the European Payments Initiative (EPI) attempts to replicate the infrastructure of global card networks while providing European citizens with a comparable alternative.
Talk Through Your Payments Setup
Tell us what you are building and DECTA's team will map which parts of the payment stack you need to own and which you can source.