What is a Low Risk Merchant Account?

A low risk merchant account is a payment processing account that lets business owners accept credit and debit card payments under terms that reflect their lower financial and operational risk. Learn what qualifies a business as low risk, how to open an account, and the main benefits and challenges.

June 06, 2025

Payment processors classify businesses as low risk based on factors like industry type, transaction volume, chargeback rates and financial stability.

Features of a Low Risk Merchant Account

Compared with high risk and medium risk accounts, low risk merchant accounts are designed for individuals and businesses seeking financial stability.

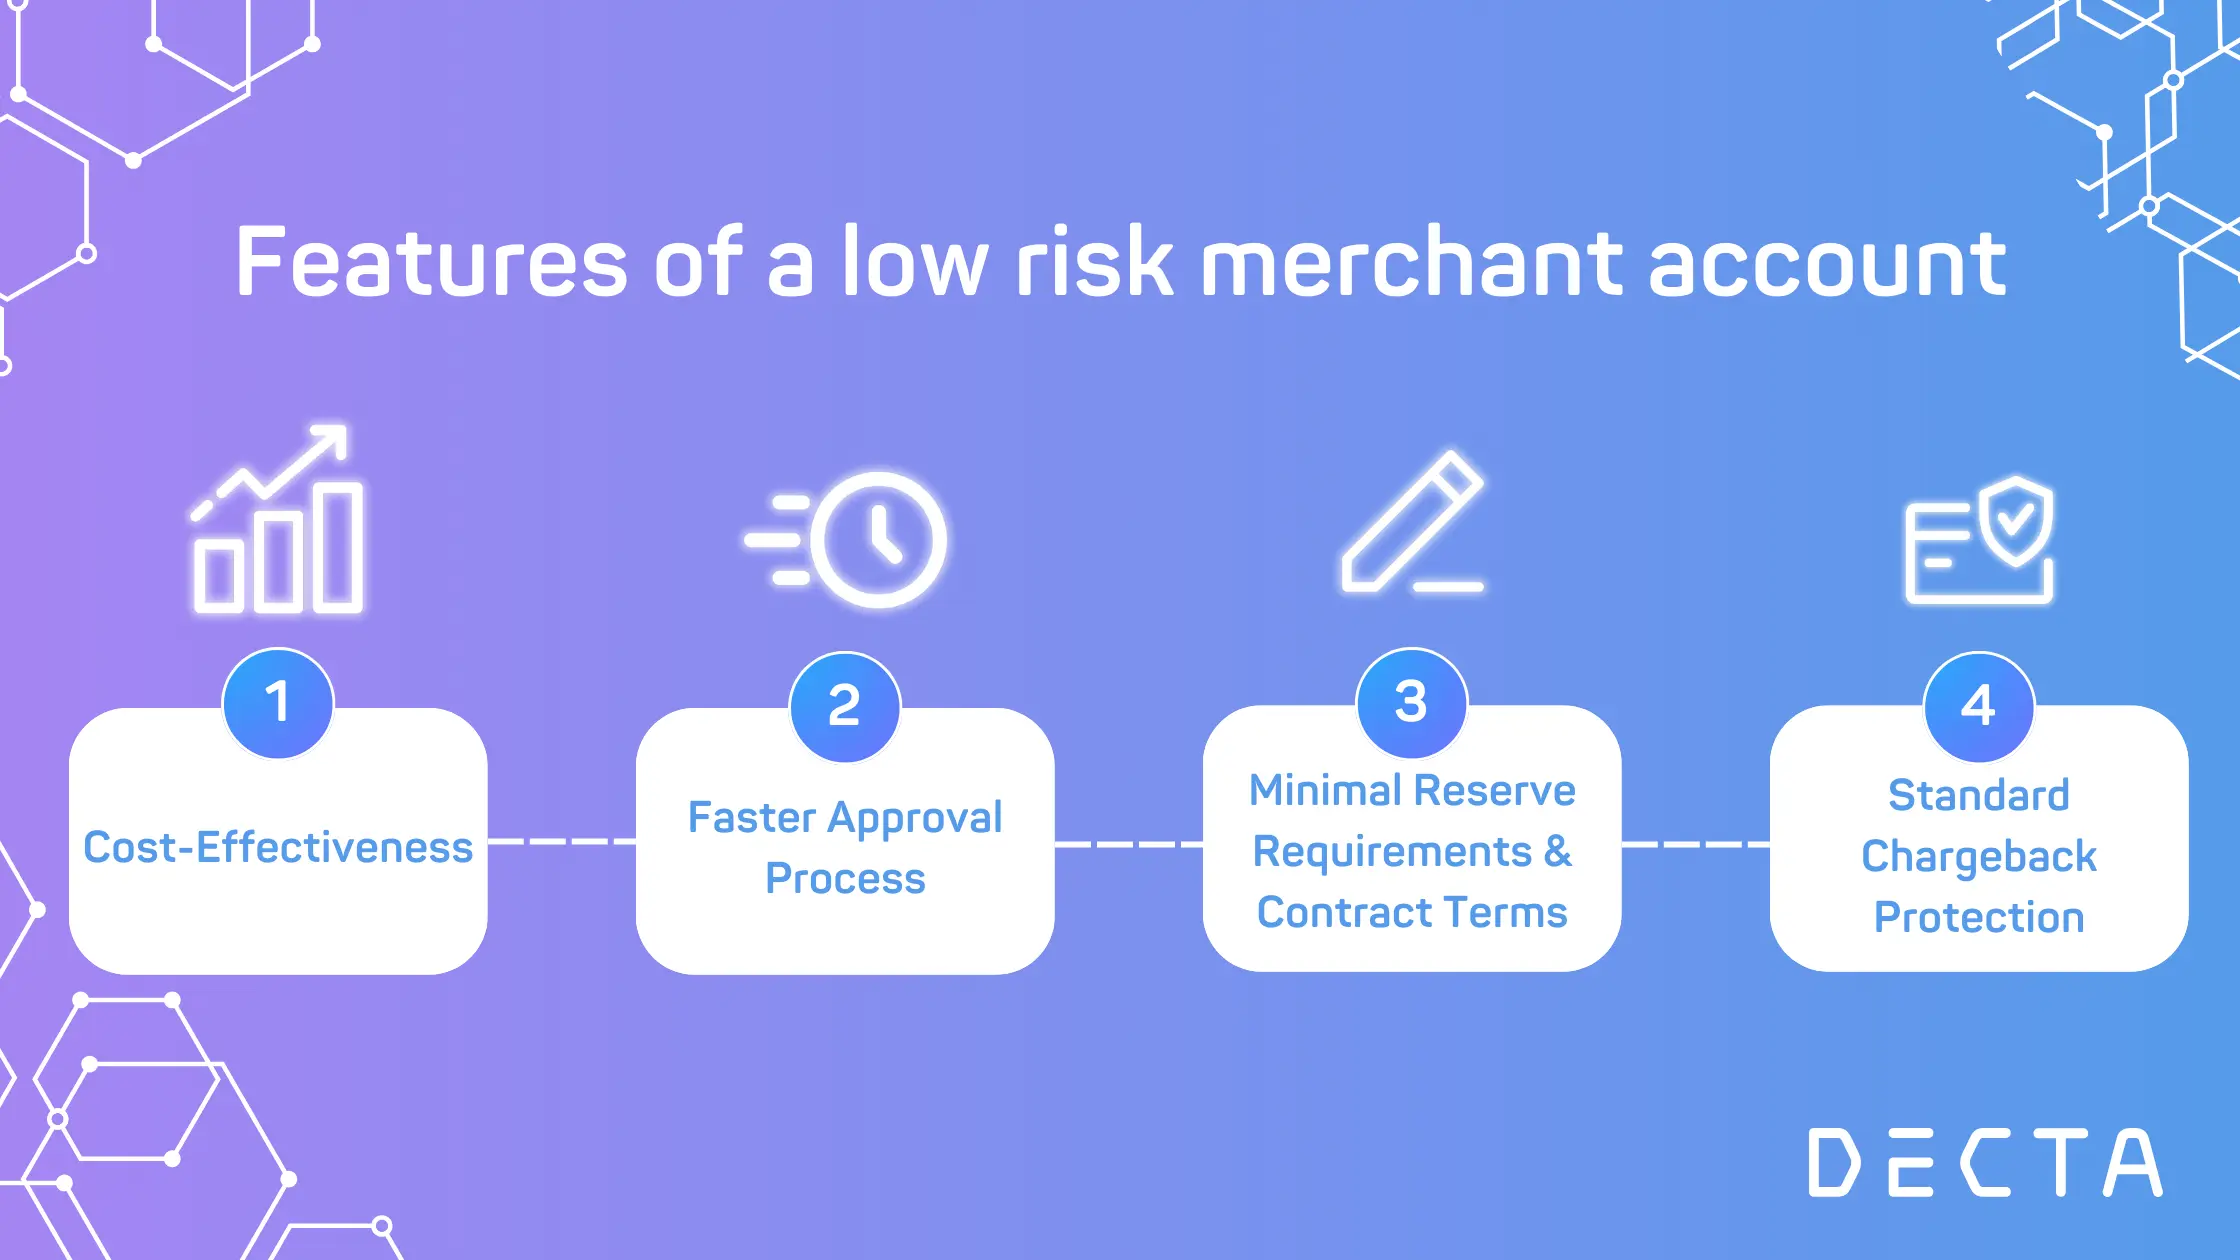
Typically, a low-risk merchant account offers the following features:

Cost-Effectiveness

Low risk merchant services typically come at a much lower cost, in comparison to high risk merchant accounts.

  • Lower Processing Fees: Reduced transaction fees from banks and processors, as well as reduced chargeback fees due to a low chargeback ratio.
  • Lower Monthly Fees: Various areas have reduced costs in low risk merchant accounts, such as lower monthly maintenance fees.

Faster Approval Process

Since low risk merchants have a stable transaction history and operate in less volatile industries such as a retail store, compared to high risk businesses operating in industries such as adult entertainment, applications are processed quickly.

Approval times range from a few hours to a few days, compared to weeks for high-risk merchant accounts.

Minimal Reserve Requirements & Contract Terms

Many low risk merchant accounts do not require a rolling reserve, meaning all earned revenue is immediately accessible.

If a reserve is required, it is usually much lower than those considered high risk.

Standard Chargeback Protection

Low-risk merchants get fewer penalties for chargebacks, making it easier to maintain a healthy account.

The payment service provider may even offer automation chargeback mitigation and fraud prevention tools to help dispute fraudulent claims.

What Makes a Business Low Risk?

Industry Type

Low risk businesses tend to be in stable industries where fraud rates are low, with consistent revenue streams.

Industries including retail, healthcare and wellness, and professional services are considered low risk compared to high risk industries, such as subscription payments and pharmaceuticals.

Processors identify a business's industry through its Merchant Category Code (MCC), a four-digit code assigned under card scheme rules, so the MCC on an application feeds directly into its risk classification.

Low Chargeback Rate

A low chargeback rate is a key factor in defining a business's risk level.

This means a business's customers rarely dispute transactions or request refunds through their banks or credit card companies.

A chargeback rate below 0.5%–1% is considered low. This feature of low risk merchants reduces the risk of account penalties and higher processing fees.

Card networks track chargeback ratios through monitoring programmes such as the Visa Acquirer Monitoring Program (VAMP) and Mastercard's Excessive Chargeback Program, and merchants who cross their thresholds face fines and closer scrutiny from their acquirer.

Businesses with quality products, clear refund policies and strong customer service often maintain low chargeback rates.

Low Average Transaction Value & Low Volume of Transactions

Eligible businesses usually have a low average transaction size. On average, in the UK, this is usually around the purchase value of £20, especially in retail and hospitality.

However, this can vary depending on context, such as the payment method. For example, contactless payments tend to have a lower value than chip-and-pin transactions.

Low average transaction value allows for steady cash flow, which is less attractive to fraudsters and easier for customer spending.

Businesses that have a lower volume of transactions are favorable to payment processors.

Domestic & Low Risk Country Transactions

Primarily, businesses that work domestically are considered lower risk because of reduced fraud and chargeback risks compared to international payments.

International transactions involve compliance with multiple regulatory systems, cross-border fees, and lower approval rates. Domestic transactions bypass this, meaning faster and simpler transactions.

Similarly, businesses dealing with low risk countries who have stable economies with low fraud rates and strong financial regulations are thought to be low risk.

Established Financial History

Businesses with a strong financial history are more likely to qualify for low-risk merchant services, especially in industries with frequent card-present transactions, where the physical card is used at a terminal and fraud risk is lower than in online, card-not-present payments.

Retail merchant accounts, for example, often benefit from stable revenue, low chargeback rates, and predictable transaction volumes, making them favourable to payment processors.

Benefits of a Low-Risk Merchant Account for Business Owners

Low risk merchant accounts offer businesses benefits beyond just cost savings.

Lower Transaction Fees

Since low risk businesses pose less financial risk to payment processors than their high risk counterparts, they can indulge in reduced transaction fees.

Lower fees per transaction help businesses maximise profits and reduce operational costs.

Faster Approvals

Another key benefit of this type of merchant account is a faster and simpler approval process compared to high risk accounts.

Since low risk businesses have stable revenue, lower chargeback rates, and minimal fraud risk, payment processors require less documentation and thorough investigation, leading to quicker approval rates.

Minimal or No Rolling Reserves

Low risk merchant accounts typically harbour little to no rolling reserves. This means payment processors don't hold a portion of the merchant's revenue as a security measure.

Therefore, allowing businesses to access their full transaction funds faster, improving cash flow and financial flexibility.

Unlike high risk merchants, who may have 5-15% of their funds withheld for months, low-risk businesses benefit from immediate or next-day access to their earnings without restrictions, making financial planning and operations smoother.

Access to More Payment Options

Lastly, a low risk merchant account provides businesses with a broader range of payment options, making transactions smoother for customers and in turn increasing sales potential.

Since these businesses are deemed financially stable and low risk, payment processors offer access to:

  • credit and debit card payments
  • digital wallets (Apple Pay, Google Pay, PayPal)
  • recurring billing
  • Buy Now, Pay Later (BNPL) solutions like Klarna and ClearPay

How to Open a Low-Risk Merchant Account

Step 1: Research Payment Processors

A merchant account is provided by an acquirer, the bank or licensed institution responsible for payment acquiring, which processes card payments on the merchant's behalf and settles the funds into the business bank account. Many businesses access an acquirer through a payment service provider (PSP) rather than directly.

Choosing a payment processor requires extensive research to ensure they meet your business needs.

Remember to research the features each payment processor offers and the fees you have to payout. Look for:

  • low transaction fees
  • effective fraud prevention tools and chargeback protection
  • fast settlement times and payout schemes
  • payment integration options
  • the processors' reputations, such as fair contract terms and high reliability and security, especially if something goes wrong

Step 2: Gather the Necessary Documents

You will need to collate supporting documentation to send alongside a completed application to your chosen provider. The specific documents required can vary depending on the provider and your business type.

For the most part, documentation will include business registration documents, bank statements, and tax returns. Make sure documents submitted contain the most recent and accurate information.

Step 3: Complete the Application

The payment processor will provide a merchant account application form that will need to be completed.

Basic business information business will be asked such as company name, company's tax ID number (EIN) and contact information. Certain merchant account providers may require additional information, including industry type, business structure, processing history and current situation.

The application may also ask you to provide details about your product types or services, payment methods you wish to accept and whether transaction processing will occur in person, online, or both.

In addition to business information, you will need to provide personal information as the business owner. This is because the merchant account provider may conduct a credit check on you as part of the underwriting process.

Remember to read through the terms and conditions and fully grasp the fees associated with the account type.

Step 4: Wait for Approval

After you have completed your application, you'll have to wait for approval from the provider, which can take days to several weeks.

Various factors can affect the approval wait time, such as incomplete or inaccurate application information, issues with supporting documentation that may involve requests for additional information. In turn, delaying the process.

Providers could conduct a review of your business background. They may evaluate factors like sales volume and processing history to assess the risk of fraud or chargebacks. This review is the underwriting process, where the provider assesses your risk profile and sets your fees, reserve and processing limits.

Present accurate and complete information on the application and a rapid response to requests for additional information or documentation, this will ensure a seamless approval process.

Step 5: Set Up Payment Integration

Once your merchant account has been approved, you can set up payment integration with your chosen provider. Depending on your needs, you can tailor the features offered for low risk merchant accounts. This tends to be a relatively simple process.

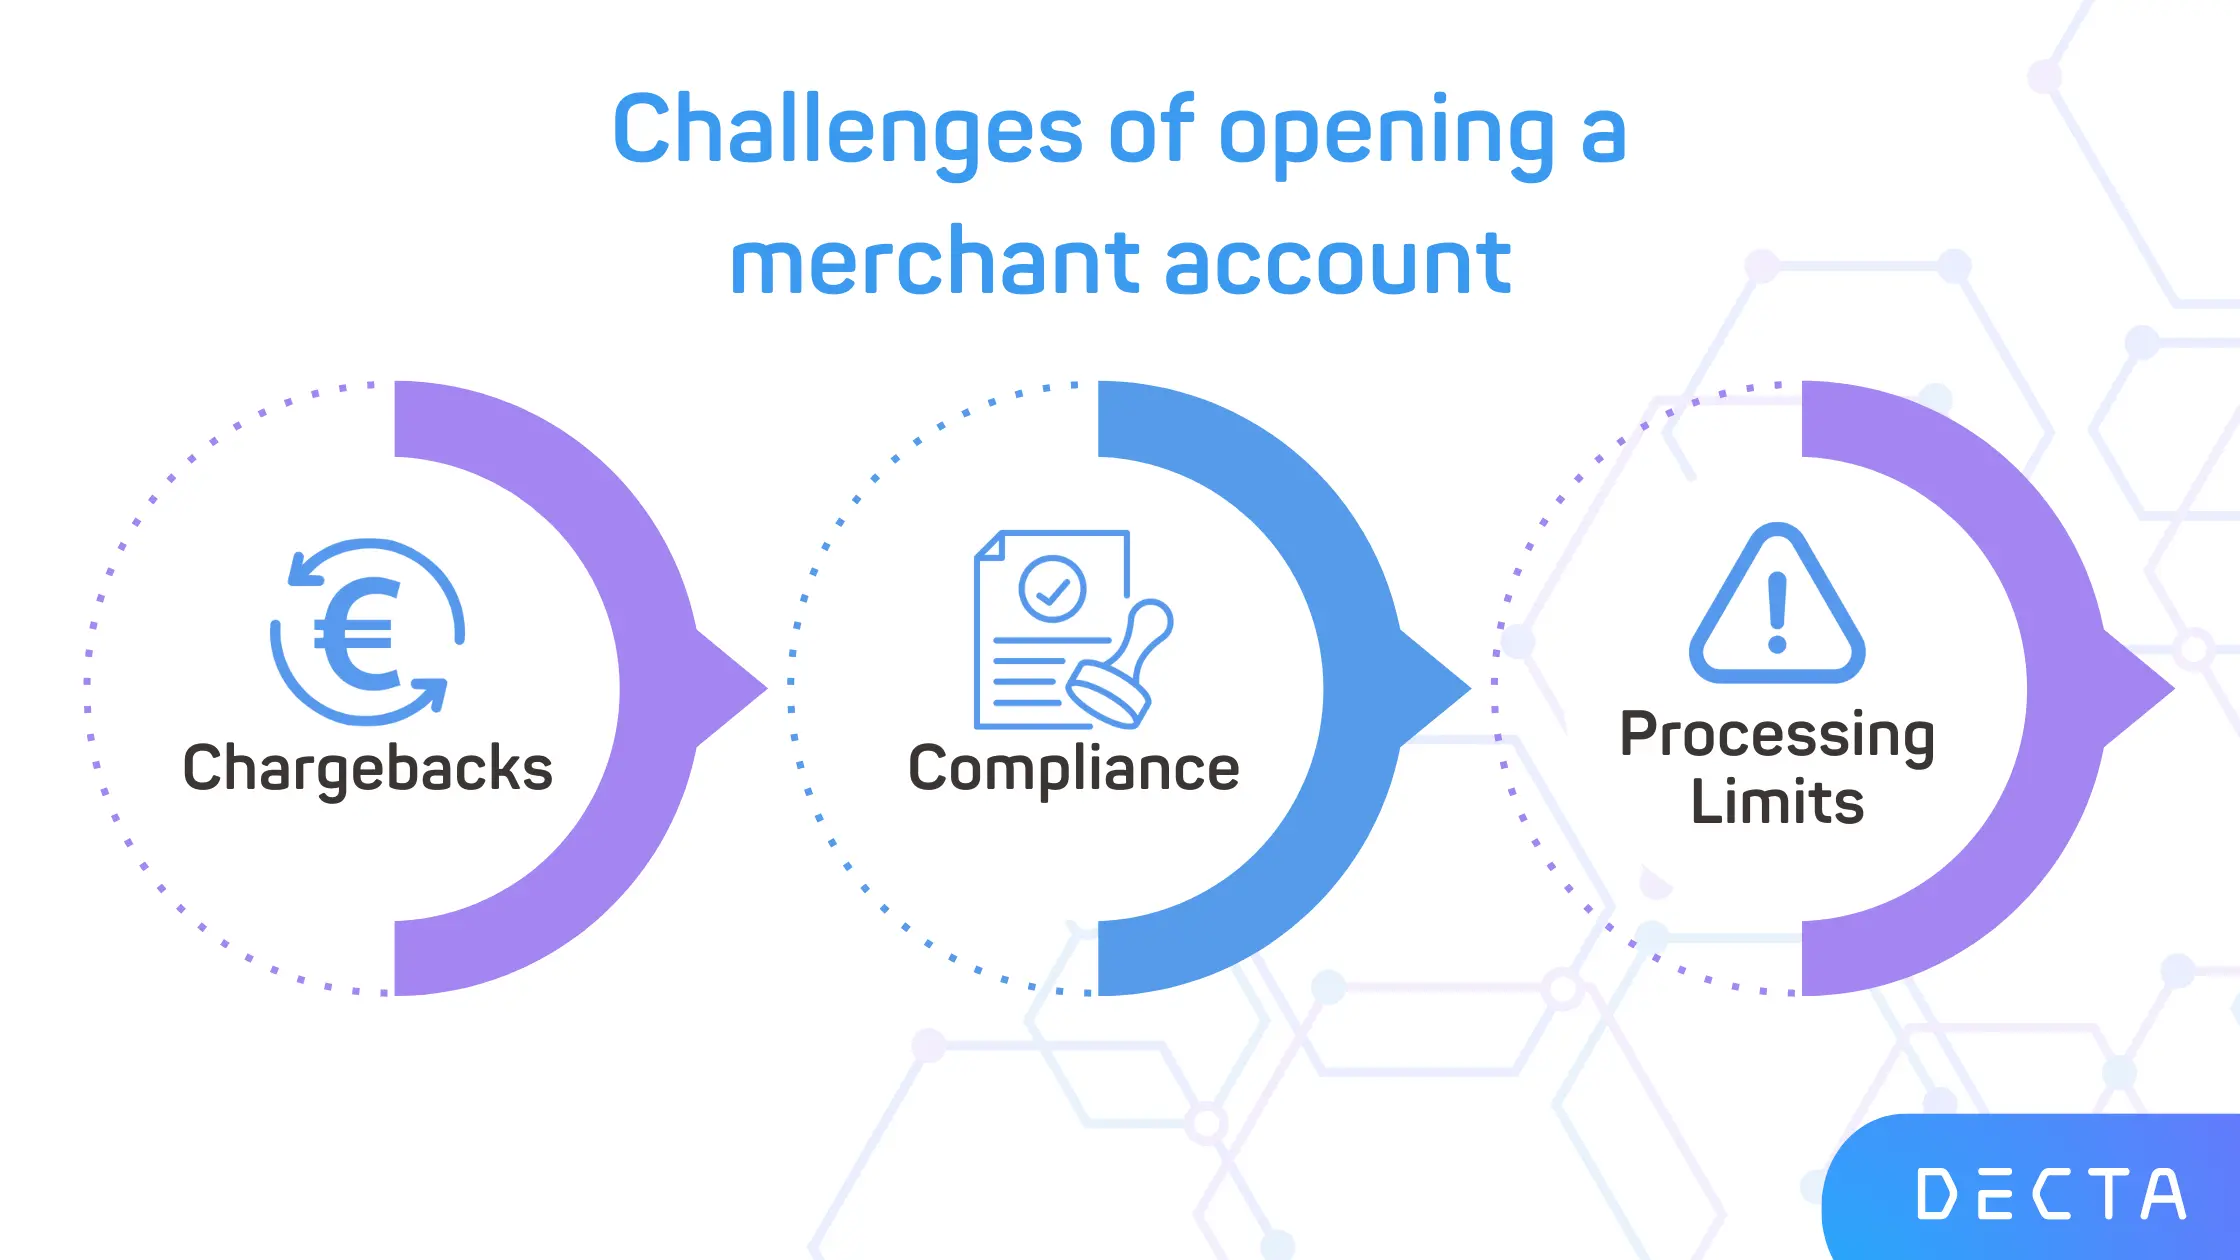
Challenges Low-Risk Merchants Should Watch Out For

Chargebacks

Even though low-risk merchants are characterised as having a low chargeback rate, chargebacks can still have a significant impact on your account.

While the risk is lower than for high risk merchant accounts, businesses should remain vigilant by implementing effective fraud prevention tools and monitoring chargeback ratios to stay under processor limits. Some providers will also offer less fraud prevention and chargeback protection.

For online payments in the EU, Strong Customer Authentication (SCA) under PSD2 adds a verification step at checkout, usually delivered through 3D Secure, which shifts liability for fraud-related chargebacks on authenticated transactions to the card issuer.

Actively reducing chargebacks helps maintain favourable processing rates and keeps steady cash flow.

Accounts closed for excessive chargebacks or fraud can be placed on Mastercard's MATCH list, which acquirers check before approving new merchants, so a closure can make it much harder to open a new account.

Compliance

Low-risk merchant accounts may still face strict compliance obligations.

They still need to adhere to PCI DSS (Payment Card Industry Data Security Standard) requirements. This means ensuring customer payment data is stored and processed securely to avoid penalties.

Remember to keep up to date with any compliance changes and updates from your merchant provider or payment processor to maintain account standing.

Payment providers can change terms, increase fees, or suspend accounts if they believe a business is becoming high-risk.

Processing Limits

Low risk merchant accounts are under processing limits and must keep within these to keep the benefits of low risk status.

As these accounts are designed for lower transaction values, payment processors may impose restrictions if monthly or single transactions exceed set thresholds.

Businesses should inquire about potential processing limits to ensure they align with their business objectives, especially if they experience factors like seasonal spikes, as these and unreported changes can even cause account freezes.

Differences Between Low-Risk & High-Risk Merchant Accounts

A low-risk merchant account is suited to businesses with stable revenue, low chargeback rates, and domestic transactions.

In contrast, high-risk merchant accounts are designed for businesses that face higher chargeback rates, fraud risks, or regulatory scrutiny.

Parameters
Typical industries
Processing fees
Rolling reserves
Approval process
Low-risk merchant account
Retail and hospitality, professional services, small-ticket eCommerce
Lower
Minimal or none
Faster, with less documentation
High-risk merchant account
Travel, gambling, subscription services (with high chargeback ratio)
Higher, due to the increased financial risk for payment providers
Common
Stricter

Choosing the right merchant account depends on your business model, transaction volume and risk profile.

How DECTA Can Help

DECTA offers secure, cost-effective payment solutions for low risk merchants, featuring transparent IC++ pricing, where interchange and card scheme fees are passed through at cost with a separate processing margin, seamless transaction processing, and diverse payment options like recurring billing and Pay By Link.

Our Acquirer Processing Platform ensures efficient, scalable payment acceptance, making it ideal for retail and other card-present industries.

With DECTA, businesses can streamline transactions, reduce costs, and enhance customer payment experiences.

Open a merchant account built around your business

Accept Mastercard, Visa, PayPal, Apple Pay and more in 50+ currencies, with flexible pricing and a dedicated account manager.

Explore Payment Acquiring